
- The stock market has recovered since October’s US non-farm payrolls report.
- Trump announced that Putin had agreed to supply diesel to the US and global markets.
- The US CPI report will shape the outlook for Fed policy.
Equities pulled back on Monday after closing last week with gains amid a rebound in the tech sector. At the same time, sentiment improved after reports that Russia would supply diesel to the global market. However, in the new week, market participants were cautious ahead of major earnings reports and the pivotal US CPI data.
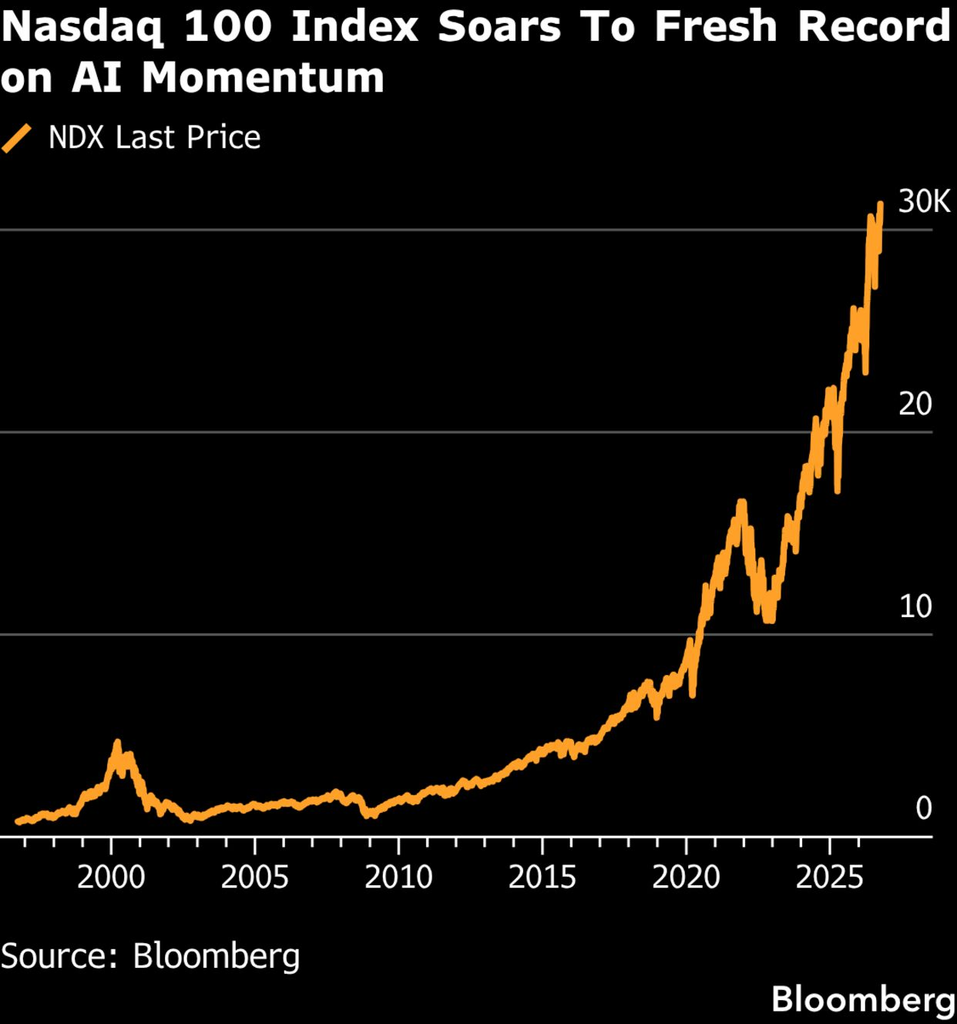
Nasdaq-100 price (Source: Bloomberg)
The stock market has recovered since October’s US non-farm payrolls report. Soft data led to a significant shift in the outlook for Fed rate-hike bets. Traders went from expecting a hike in October and December to just one such move by the end of the year. As a result, yields pulled back slightly, and the tech sector rebounded, sending the Nasdaq-100 to fresh highs.
At the same time, market participants paid attention to developments in the Middle East. Risk appetite improved after reports that the G7 countries plan to release diesel and crude stocks to help lower fuel prices. Notably, Trump announced that Russia’s president had agreed to supply diesel to the US and global markets. The move will ease inflation worries, easing pressure on central banks to hike interest rates.
Furthermore, traders reacted to news on Thursday that Trump was not really keen on signing a deal with Iran. He threatened to resume bombing the country before the US midterm elections in November. Stocks collapsed before pulling back in the next session after he retracted his statement. Nevertheless, market participants still expect the conflict to resume after the elections.
Meanwhile, major banks are set to release their earnings reports this week, among other big companies. Experts remain optimistic about earnings, which have remained strong despite the war in Iran. However, the conflict has kept a lid on gains and could continue to do so.
“The conflict is one thing holding this market back from really reflecting how powerful the near-term earnings story is,” Michael Monaghan of Founder ETFs told CNBC. “A more violent, more kinetic, more border-expanding war is not priced into the market.”
Elsewhere, the US CPI report coming out on Wednesday will shape the outlook for Fed policy before the October meeting. Economists expect an acceleration in annual and monthly price pressures. Upbeat numbers will increase pressure on the Fed to hike, sending equities lower. On the other hand, soft numbers will allow last week’s rally to continue.